

VCs across the world are pouring capital into AI startups, often repeating the same bold claim: “AI will replace most jobs in the next decade.”
But does that mean AI will replace venture capitalists as well?
Are VCs pouring money into a technology that could eventually make them obsolete?
To move beyond speculation, we at TheVentures—an early-stage VC firm based in Seoul, Korea—decided to run a real experiment. Instead of debating whether AI could replace VCs, we tried to build one.
This post reflects on that experiment: our initial hypothesis, how we built an AI investment analyst, and what we learned from deploying it in real investment workflows.
What We Set Out to Build
Even the term ‘AI investment analyst’ is very broad. What did we actually mean by it? What goals were we trying to achieve?
We believed that in any industry, there are two major steps to achieving AI transformation.
You build AI systems that perform the same tasks human workers do, with a similar level of output quality.
Then, you build AI systems with the expectation that they will eventually outperform human workers.
At TheVentures, we interpreted the first step as building an AI Analyst that could handle the same tasks our teammates currently do, but faster and more automatically, with minimal human intervention.
So for now, it wasn’t about experimenting “Can we rely on AI to make better investment decisions than we can?”
Rather, this AI analyst needed to make investment decisions similar to ours. We wanted it to function as a super-charged version of our investment team: fast, consistent, and able to work without fatigue.
So the goal became clear.
Build an AI analyst that works, thinks, and makes investment decisions like the existing human investors at the firm.
Then test whether that AI analyst can meaningfully contribute to improving and optimizing our workflow, increasing productivity without requiring proportional increases in time, cost, or headcount.
The Real Challenge: Early-Stage Investing
TheVentures invests primarily at the Pre-Seed, Seed, and Pre-A stages. At this stage, financials are sparse or nonexistent, and quantitative analysis often adds little value.
In later-stage investing, where companies are more established and data-rich, research has already shown that LLM-based systems can outperform human analysts in screening and evaluation.
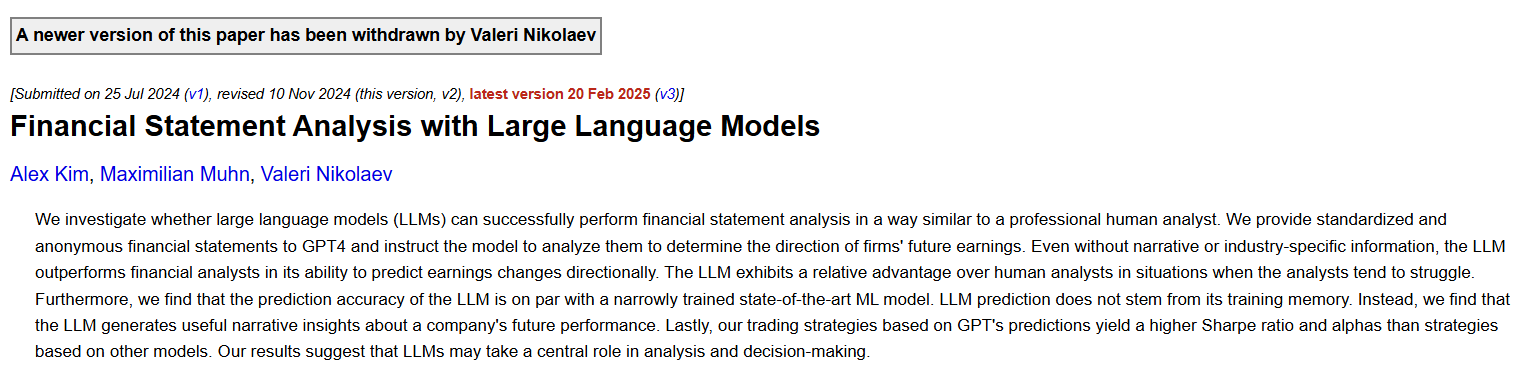
Early-stage investing is different. It is widely believed to be irreducibly human, shaped by founder quality, context, narrative, and intuition, and highly unpredictable.
Thus, two concerns stood out.
First, early-stage investing is inherently paradoxical: if everyone agrees something is good, returns are usually mediocre. Yet LLMs are optimized to generate the most statistically likely, “reasonable” responses.
Second, the internet contains far more shallow or misleading writing about startups than genuinely insightful analysis. If an LLM’s pretraining data is noisy, why should we expect nuanced early-stage judgment?
These concerns were the biggest challenges we had to overcome to successfully deploy an AI investment analyst.
Rethinking Intuition
The solution came from reconsidering what we mean by intuition.
Intuition is often treated as something mystical. In practice, it is the result of processing many weak signals extremely quickly. The logic exists; we simply do not observe it consciously.
If that process can be decomposed—if we can identify what signals matter and how they are combined—intuition becomes something that can be approximated by a system.
Not by a single model, necessarily, but by a structured system of multiple agents, each responsible for interpreting different signals and synthesizing judgments.
From here, the systemic design and planning for our AI investment analyst began.
The Actual Implementation
So, we started not with models, but with people.
We spent significant time understanding how everyone on our investment team thinks. Our tech lead, Jace Hwang, conducted deep interviews, reviewed deals alongside individual investors, and intentionally challenged their interpretations to surface implicit assumptions behind their judgments.
We effectively “pair programmed” this system alongside our investment team, observing how decisions were formed, debated, and sometimes reversed. We later named this system “Vicky.”
Through this process, we were able to clearly articulate what signals were being used, how they were interpreted, and how they could be translated into prompts and context engineering.
The result was an LLM-based, multi-agent AI investment analyst embedded directly into our internal dashboard and workflow. It consists of:
A multi-agent system that deploys specialized quantitative and qualitative reasoning and evaluation agents for each investment criterion for a given company.
The use of different LLM providers where appropriate, allowing each component to leverage the strengths of specific models.
Retrieval-augmented generation (RAG) connected to the company’s internal database and knowledge base to fetch relevant data and strengthen company analysis and memo generation.
When information about a company enters our system, such as a pitch deck, founder profile, one-pager, or meeting transcript, Vicky processes these materials and automatically generates a structured company summary report for our team to review. On top of that, it produces its own investment rating (Yes, Maybe, No) along with a written rationale explaining the reasoning behind the call.
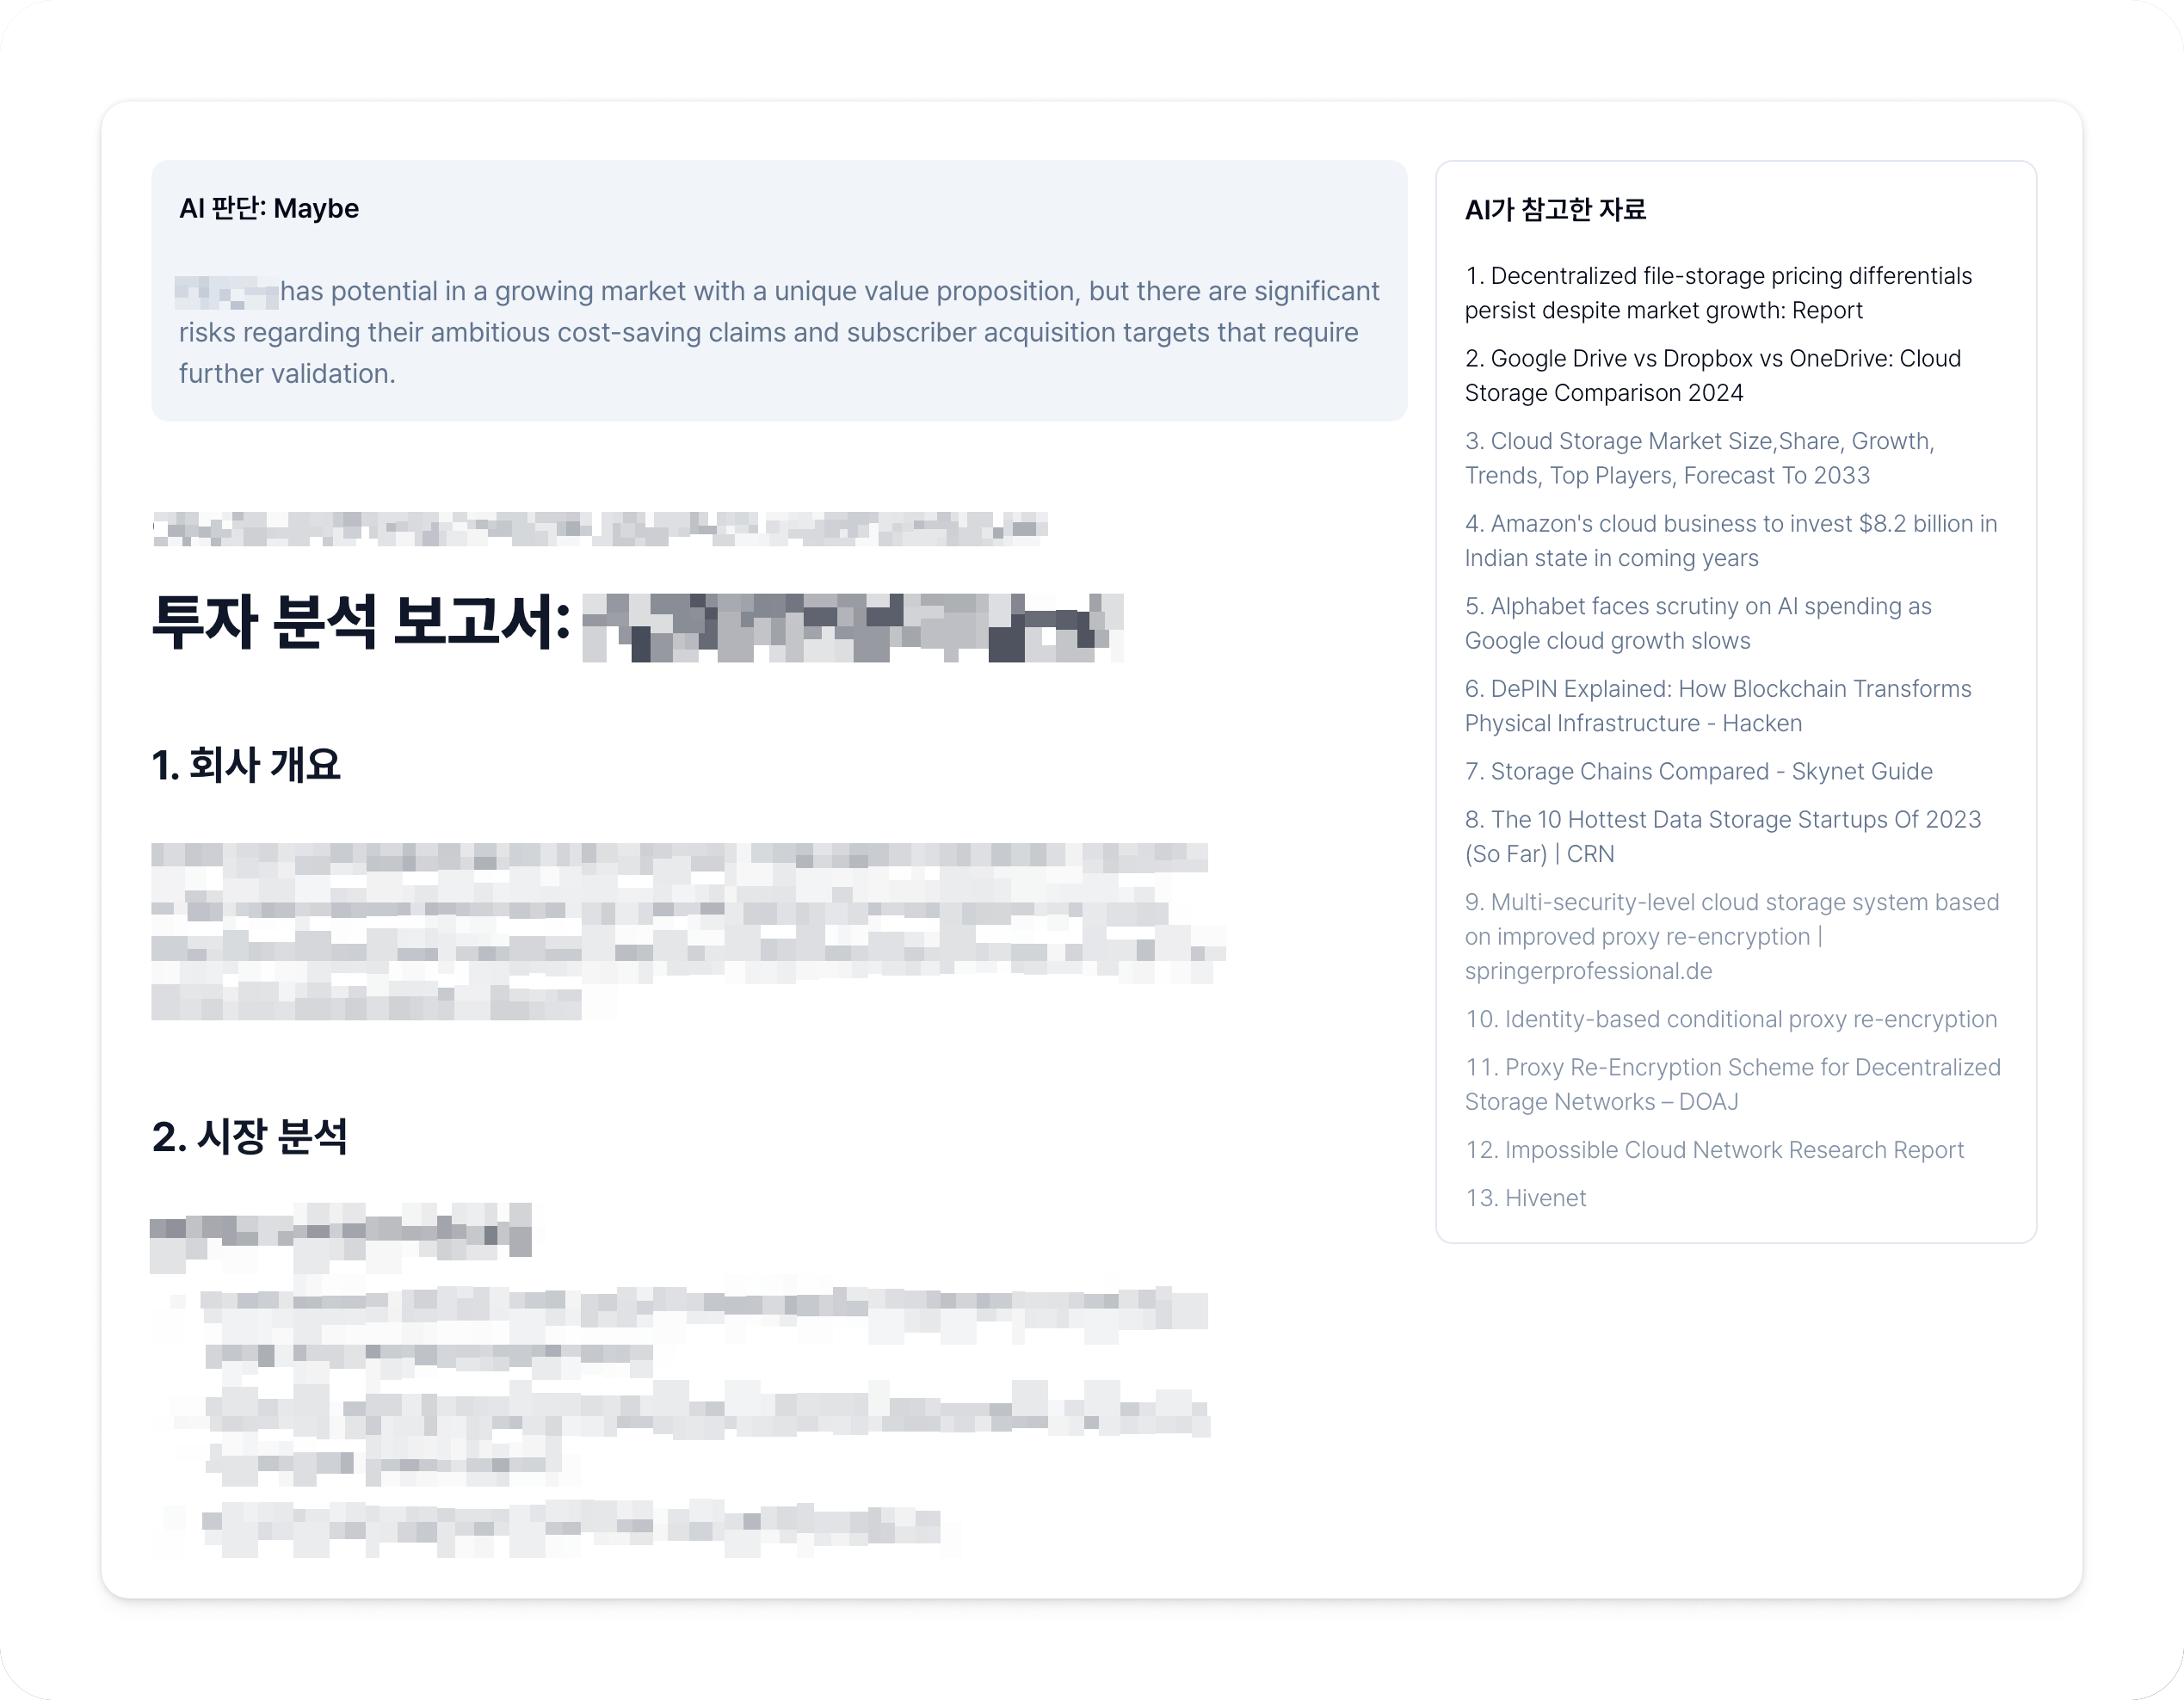
Vicky does not make final decisions yet. But by the time a human investor reviews a deal, the initial synthesis, analysis, and framing of the company are already complete.
What Actually Happened
After six months of deploying and iterating on Vicky, the alignment between its recommendations and our human investors’ conclusions was approximately 87.5%.
Given that our initial goal was to build an AI analyst that mirrors our human investors’ decision-making, achieving 87.5% alignment is a strong result.
What used to take roughly a week to produce an investment memo now takes about one hour.
What used to be a four-to-six-week response time has now been reduced to one week. We now review new batches of startups and founders on a weekly basis, positioning us among the fastest decision-making early-stage firms in Korea.
We plan to further reduce the response time to three days by this spring.
More unexpectedly, Vicky began recommending meetings with teams that some investors initially overlooked. In several cases, these did not immediately lead to investments, but they surfaced teams with clear long-term potential—teams we likely would not have met otherwise.
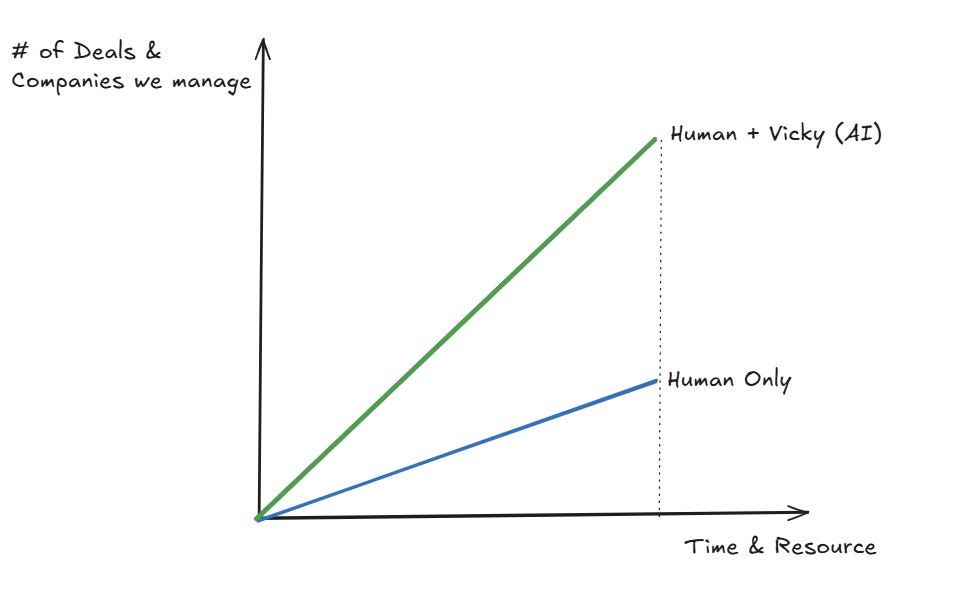
These results have led us to believe that Vicky is already meaningfully contributing to our workflow. It allows us to review more companies, more quickly, even while operating with the same resources as before. It is also not an unusually expensive or heavy system to run. In practice, generating a single investment rating typically takes between one and two minutes, and in more complex cases up to three or four minutes.
We have concluded that our step-one deployment of an AI investment analyst has been successful, which now motivates us to move on to step two: making Vicky smarter and, eventually, a better investor than ourselves. We also plan to share the lessons we learn along the way, so please stay tuned.
Also, if you’re interested in learning more about our approach to building an AI-driven VC, you can check out a slide deck created by our CEO and managing partner, Sean Kim.
If you're interested in discussing potential investment opportunities or collaboration with TheVentures, we'd love to hear from you at info@theventures.vc (general) or duck@theventures.vc (research). If you’re an early-stage founder currently raising, feel free to reach out to us here.
Special thanks to Jace Hwang
About the initial two concerns:
1) if everyone agrees something is good, returns are usually mediocre. Yet LLMs are optimized to generate the most statistically likely, “reasonable” responses.
2) The internet contains far more shallow or misleading writing about startups than genuinely insightful analysis.
In fact, these two issues apply not only to LLMs but also to humans—including highly intelligent investment professionals—who share the same vulnerabilities and carry significant biases. Once we acknowledge these human limitations, the resistance to giving AI a greater voice in decision-making naturally diminishes.
Nice.
Would be curious to know who was more bullish in the 12.5% of cases where AI and humans disagreed.
Were there clear patterns of reasons to inform the disagreement?